Primary and urgent care
Unlimited in-network visitsOffice visit charges are covered at 100% for everyday illnesses, minor injuries, and routine concerns.
For enrolled employees; eligibility and covered charges follow The Plan. Supplemental health + wellness. Real savings.Changes the page to larger text, wider spacing, shorter line lengths, and enhanced contrast.
For employers with W-2 employees in any industry
The Plan adds primary and urgent care, 24/7 virtual doctors, mental health support, common prescriptions, preventive services, and eligible family access without replacing major medical.
Everyday medical, mental health, prescription, preventive, and eligible family support.
See what employees receive ↓Paycheck + employer opportunityPositive before election. Model your savings.Screen the employee paycheck result, then estimate the company opportunity from projected participants.
Open the calculator ↘Primary and urgent care, virtual doctors, mental health support, everyday prescriptions, prevention and monitoring, plus eligible family access and virtual veterinary guidance. Major medical stays in place.
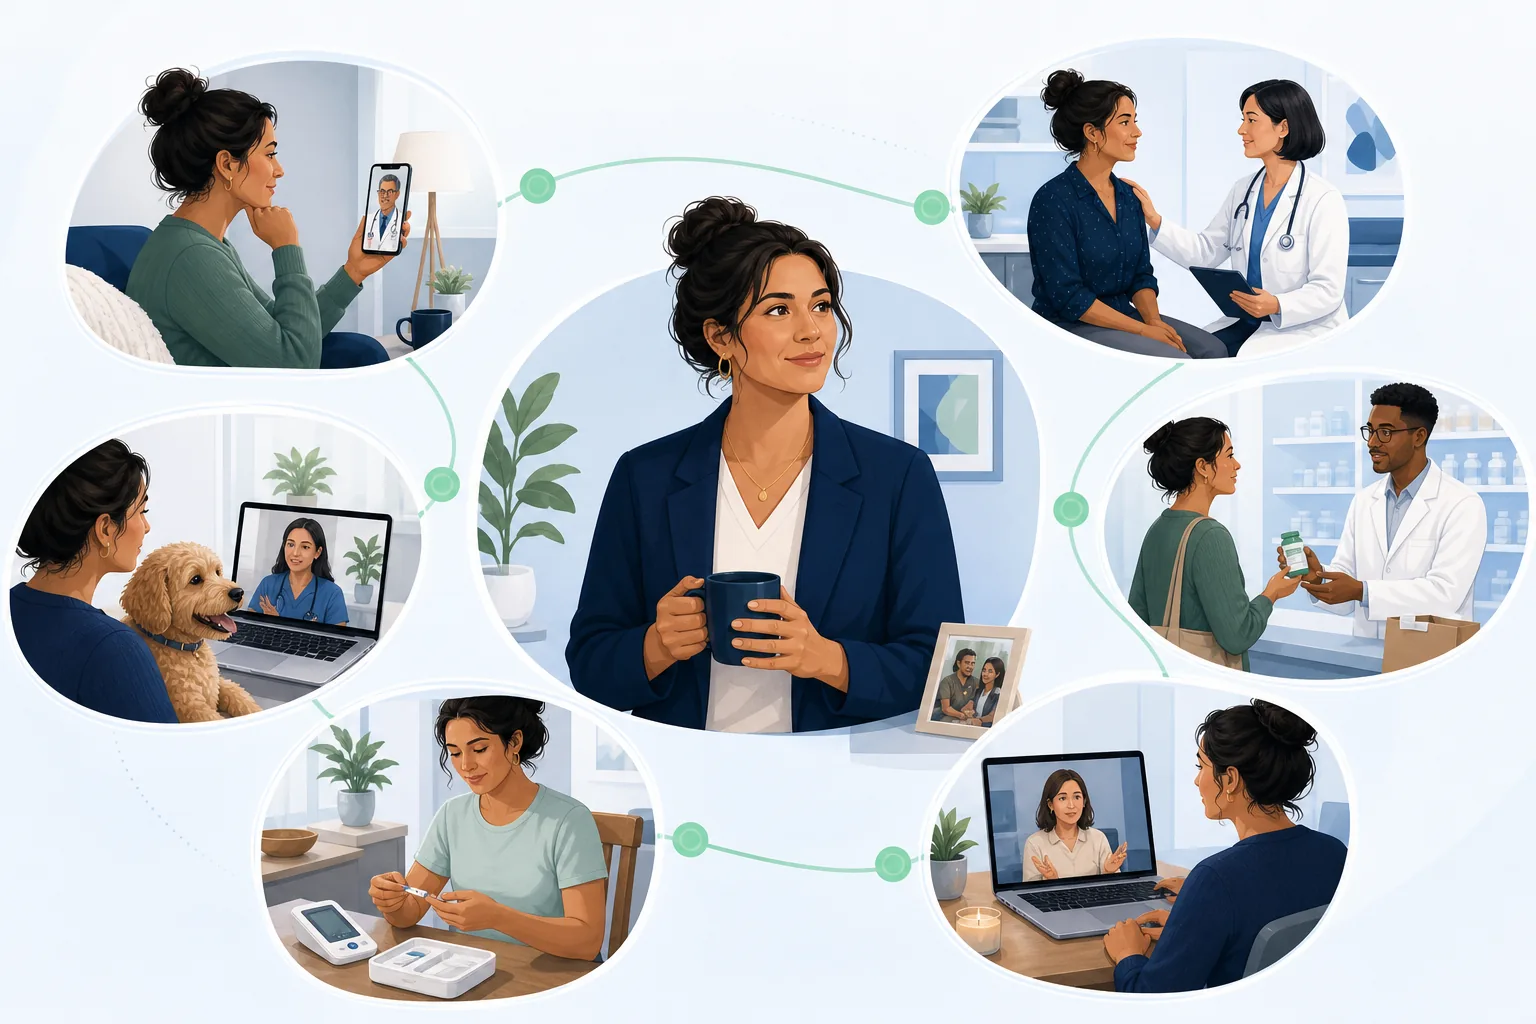
Primary care, prescriptions, counseling, preventive services, health monitoring, eligible family access, and virtual veterinary guidance.
Office visit charges are covered at 100% for everyday illnesses, minor injuries, and routine concerns.
For enrolled employees; eligibility and covered charges follow The Plan.A broad formulary makes many everyday prescriptions available at no member cost.
Employee plus eligible family access.Connect from home or on the road for evaluation, guidance, and prescriptions when clinically appropriate.
Employee plus eligible family access.Confidential help for anxiety, depression, stress, relationships, and family concerns-before a difficult season becomes a crisis.
Employee plus eligible family access.Plan-covered preventive services and health monitoring can help employees spot changes sooner and have better-informed care conversations.
General wellness purchases are not represented as tax-qualified medical expenses.Several care services may extend to an enrolled employee's eligible spouse and dependents, with virtual veterinary guidance available for household pets.
Family eligibility and virtual veterinary guidance follow the controlling plan documents; veterinary guidance is not a tax-qualified medical expense.Mental health support is a core part of The Plan.
Exact services, networks, providers, formularies, availability, coverage, and family eligibility are governed by the final plan documents and approved employer configuration.
Start with the employees you expect to meet the eligibility and positive-paycheck criteria, then apply a participation rate you would actually bet on.
A gross-to-net illustration shows each deduction, employer contribution, taxable amount, and Plan cost before an employee is invited to elect The Plan.
Only employees who meet the criteria and show a positive projected paycheck result proceed to voluntary election.Qualifying salary-reduction contributions used to purchase qualifying health coverage may be excluded from FICA wages.
Your savings analysis uses your workforce, payroll, Plan costs, and actual tax treatment.Illustrated at 80% projected participation. Change the inputs to match your workforce. The confidential review replaces this public scenario with your payroll, your eligibility results, real Plan costs, and the tax treatment your advisors will stand behind.
Industry does not decide fit. Size, ownership, payroll system, current coverage, and who has to sign off decide how the review runs.
Owner-led • lean administration • one payroll relationship
View review requirements ↗Established coverage • cross-functional approval • multiple payroll groups
View review requirements ↗Multiple companies • repeatable diligence • EBITDA focus
View review requirements ↗Distributed workforce • multiple systems • formal governance
View review requirements ↗For agents and brokers
If you already sit across the table from employers, this is something you can add without rebuilding your book. We sign a referral agreement, get you appointed, and you keep selling the relationships you already have.
Small business, middle market, private equity portfolios. If they run W-2 payroll, the conversation works.
Payroll screening, plan documents, the tax questions, and the diligence file. You do not have to become a Section 125 expert to sell this.
Thirty minutes on Zoom covering the referral agreement, how appointments work, and what you earn. No deck, no group webinar.
Why prevention matters
When a doctor visit is easy to get, employees ask the question they have been putting off. Most of prevention is nothing more complicated than that.
Access
Use
Risk
Chronic disease drives much of the nation's $5.3 trillion in annual healthcare costs. CDC and CMS emphasize prevention and early detection. The workplace can expand that access years before Medicare eligibility.
What advisors validate
Qualifying salary-reduction contributions for qualifying health coverage may be excluded from FICA wages when the written plan and actual operation satisfy the applicable requirements. Finance, payroll, tax, and plan advisors verify the final treatment.
Eligible employees elect qualifying health coverage under the employer's written Section 125 plan.
Pre-tax salary reduction is applied only to qualifying coverage described by the written plan and supported by applicable tax rules.
Cash rewards, fixed payments, premium refunds, and amounts unrelated to substantiated medical expenses are not represented as tax-free.
Finance verifies deductions, employer funding, vendor invoices, taxable amounts, and actual payroll-tax results after launch.
The approval file
Tax mechanics, responsibilities, privacy safeguards, and operating procedures, in one record instead of six email threads.
Plan Document and plain-language Summary Plan Description.
Section 125 mechanics, elections, and payroll treatment.
Eligibility rules and nondiscrimination testing.
ERISA duties, claims, notices, and fiduciary roles.
HIPAA roles, data access, safeguards, and vendor agreements.
Network, formulary, coded interactions, support, and reporting.
Confirm fit, find out who actually qualifies, complete diligence, then prepare the rollout. Nothing moves forward on an estimate alone.
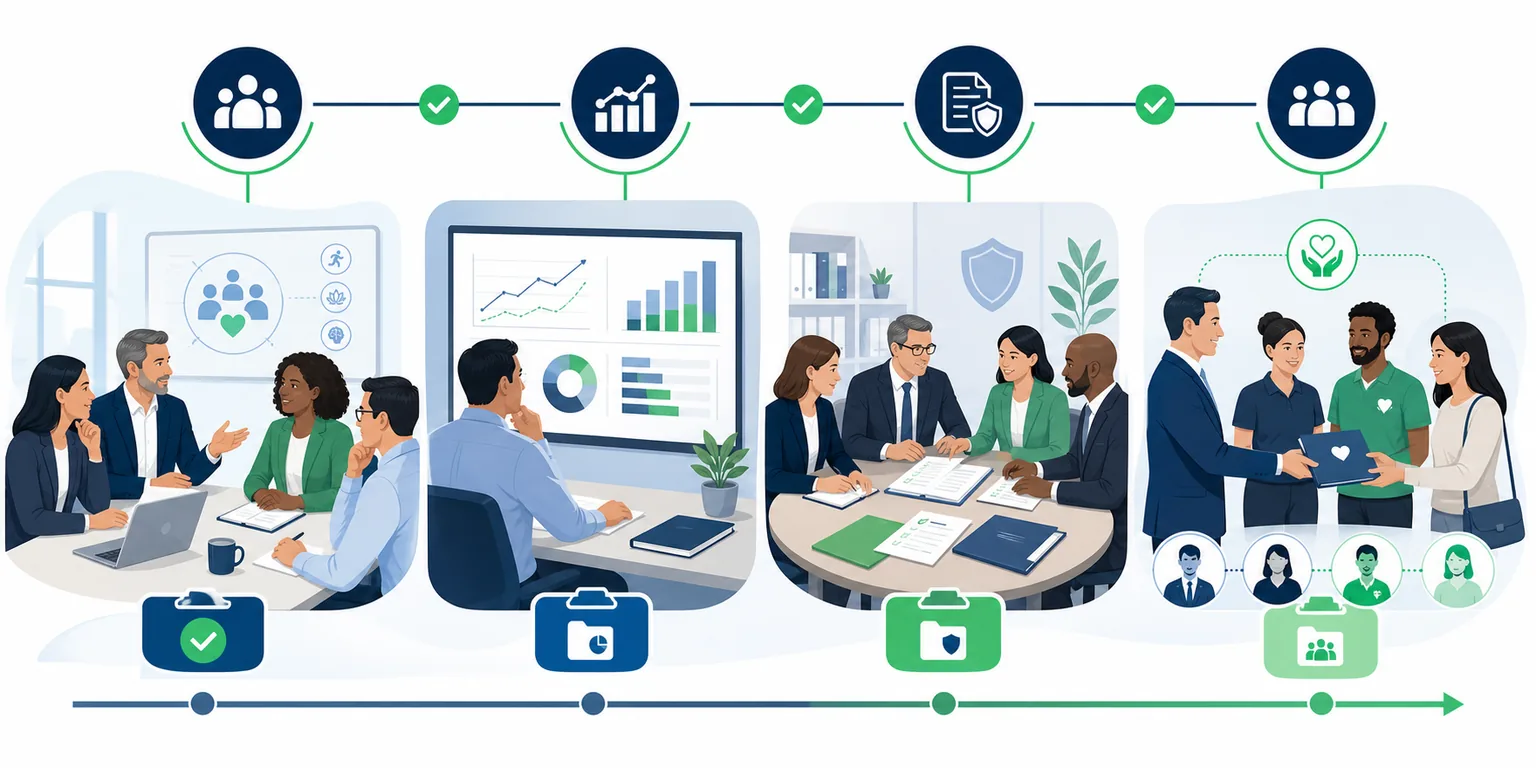
Workforce information, payroll estimates, advisor review, and implementation.
Review your workforce, coverage, payroll, timing, and decision criteria.
Use one secure payroll period to identify employees who meet the criteria and show a positive projected paycheck result.
Your advisors review the structure, documents, responsibilities, and rollout plan.
Coordinate setup, payroll mapping, communication, enrollment, and support.
Before you book
The calculator and the approval file cover the economics and the compliance. These are the practical ones.
No. It is supplemental health and wellness designed to work alongside existing major medical coverage.
Only business context. Do not send payroll or health information here. If you proceed, we establish a secure payroll-review process.
Usually an executive sponsor, finance, payroll, legal or tax counsel, and the advisor responsible for existing health coverage.
The operating model covers enrollment, support, payroll reconciliation, reporting, administration, and escalation.
Workforce size, payroll environment, current coverage, and what you are trying to decide. We'll come back with whether it fits, what we would need to model it properly, and who should be in the room.
No employee health information, Social Security numbers, or payroll files are needed here.